Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
France : Immigration, Asile et Opportunités d'Emploi
France : Immigration, Asile et Opportunités d'Emploi
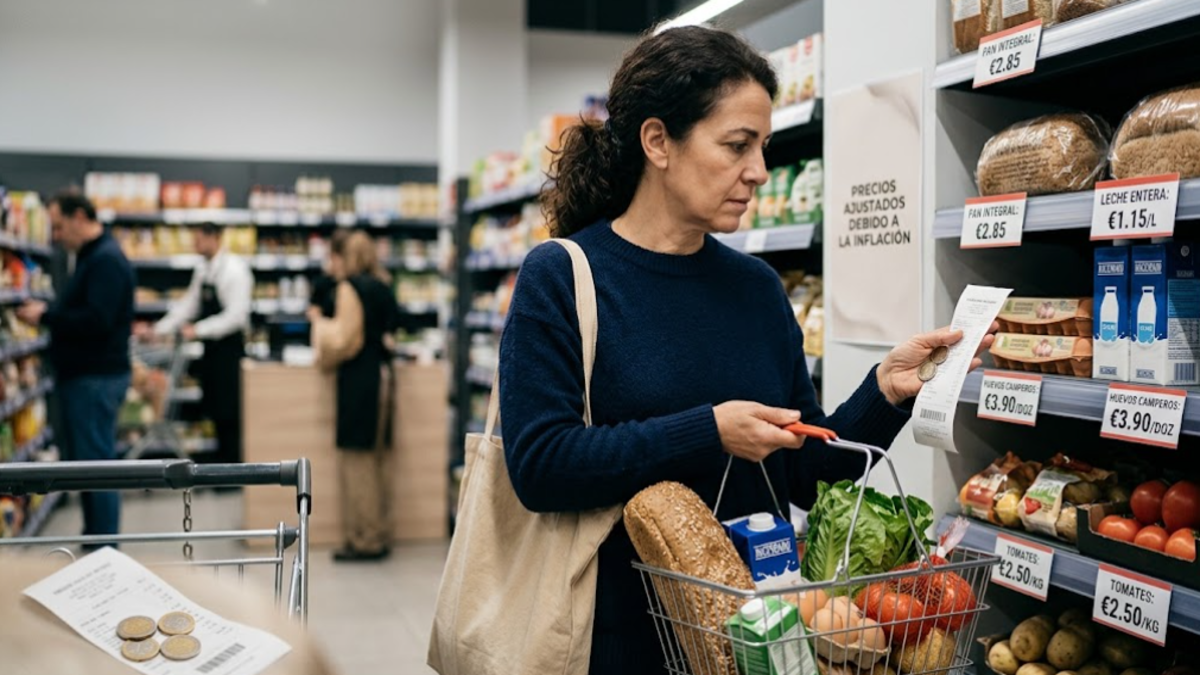
Inflation reduces purchasing power when the prices of goods and services rise faster than household incomes. For families, pensioners and workers, the consequences can be felt in everyday expenses, from groceries and electricity to transport, rent and loan repayments. The challenge is not simply that prices increase, but that income often fails to keep pace with the cost of living.
In Spain, the latest available figures illustrate the pressure. According to the National Statistics Institute (INE), the annual Consumer Price Index (CPI) inflation rate reached 4.9% in September 2026, based on its preliminary estimate published on 29 September. This followed 4.3% in August. The preliminary estimate for underlying inflation, which excludes unprocessed food and energy products, rose to 3.1%.
These figures show why inflation remains a significant economic issue even for households whose wages or pensions have increased. Understanding how inflation affects purchasing power can help consumers make better financial decisions and assess whether economic measures are delivering meaningful relief.
Inflation is the general increase in the prices of goods and services over time. It is usually measured through a consumer price index, which tracks the changing cost of a representative basket of household purchases.
Purchasing power describes how much a person can buy with a given amount of money. When prices rise but income stays unchanged, the same salary buys fewer goods and services.
For example, consider a household with a monthly budget of €2,000. If the prices of everything it buys increased by 5% on average, maintaining the same standard of consumption would require approximately €2,100 a month.
If its income remained at €2,000, the household would face a €100 monthly shortfall relative to that illustrative budget. In practice, the impact depends on the household’s spending habits because individual expenses do not all rise at the same rate.
The distinction between inflation and the cost of living is therefore essential. Inflation measures how quickly prices change, while the cost of living reflects the money needed to maintain a particular standard of life.
The INE’s September preliminary estimate points to renewed price pressure in Spain. The annual inflation rate increased by six-tenths of a percentage point from August, while underlying inflation also edged higher.
The main figures are:
Indicator | August 2026 | September 2026 preliminary estimate |
|---|---|---|
Annual CPI inflation | 4.3% | 4.9% |
Annual underlying inflation | 2.9% | 3.1% |
Monthly CPI change | 0.7% | 0.3% |
Source: Spain’s National Statistics Institute (INE). September figures are preliminary estimates.
The INE attributed the increase in headline inflation partly to fuel and lubricant prices for private vehicles, which rose in comparison with the previous year’s movement. Package holiday prices also contributed because they fell less than they had during the same period a year earlier.
These details matter because inflation is influenced not only by current price changes but also by what happened in the comparison period.
A higher annual inflation rate does not mean every product became more expensive by the same percentage during September. Nor does a lower monthly rate necessarily mean prices are falling. It means prices increased more slowly during that month than during the previous one.
The September figures were preliminary when published. They should therefore be distinguished from the final statistical results.
The national inflation rate is an average. It does not necessarily reflect the price increases experienced by every household.
A family that spends a large share of its income on food, heating and transport may feel inflation more sharply than a household with fewer essential expenses. Likewise, renters facing a rent increase can experience greater financial pressure than homeowners with a fixed-rate mortgage and stable housing costs.
Several factors explain these differences.
Food, housing, electricity and transport are difficult to eliminate from a household budget. When these expenses rise, families may have little choice but to reduce spending on clothing, leisure, education or other purchases.
A pay rise does not automatically protect purchasing power. If a worker receives a 2% salary increase while consumer prices rise by 5%, the worker’s real income declines, assuming the same consumption basket.
In this example, the change in purchasing power is approximately −2.9%, calculated by comparing the increase in income with the increase in prices.
Money held in a low-interest account can gradually lose purchasing power. If savings earn less than the inflation rate, their real value declines, even though the account balance remains unchanged.
This does not mean every household should move its savings into investments. The right approach depends on emergency needs, time horizons, risk tolerance and the possibility of losing money.
Inflation and interest rates are related, but they are not the same thing. When the European Central Bank changes its policy rates, borrowing conditions across the euro area can change too, although the effects take time and depend on individual financial products.
Households with variable-rate loans may be exposed to changes in borrowing costs. Those with fixed-rate loans generally have more predictable scheduled repayments, although their other living expenses can still rise.
Spain is not experiencing inflation in isolation. Eurostat’s preliminary figures for September 2026 put annual inflation in the euro area at 3.8%, up from 3.2% in August.
Spain — CPI, preliminary
Euro area — HICP, preliminary
These figures use different consumer price indices. The harmonised index is designed for international comparison; Spain’s national CPI measures domestic consumer price developments.
The figures suggest that price pressures were stronger in Spain than in the euro area overall, but comparisons must use consistent indicators where possible. Eurostat’s harmonised measure puts Spain’s annual inflation rate at 5.0% for September, compared with 3.8% for the euro area. Both figures were preliminary estimates at the time of publication.

Energy was a major source of pressure across the euro area. Eurostat estimated its annual inflation rate at 18.8% in September, compared with 14.3% in August. Services inflation stood at 3.2%, while food, alcohol and tobacco recorded 1.4%.
These figures illustrate why a headline inflation rate must be examined alongside its components. A surge in energy prices can raise household bills directly and increase costs for businesses, including those involved in transport and production. Whether those costs are passed on to consumers, and how quickly, varies by sector.
Consumers cannot control national inflation, but they can take practical steps to understand and manage its effects. These measures will not eliminate the impact of rising prices, and some households have less flexibility than others.
Start by examining spending over the past two or three months. Separate essential costs from discretionary purchases and identify which categories have increased most.
A simple budget can include:
Housing: rent, mortgage payments, insurance and maintenance.
Utilities: electricity, gas, water and internet.
Food: groceries, household essentials and meals outside the home.
Transport: fuel, public transport, insurance and vehicle maintenance.
Financial commitments: loan repayments, fees and other regular obligations.
Discretionary spending: subscriptions, entertainment and non-essential purchases.
The purpose is not to cut every expense. It is to identify where spending can be adjusted without compromising essential needs.
Comparing unit prices rather than package prices can reveal which products offer better value. Planning meals, reducing food waste and reviewing recurring subscriptions can also help.
For utilities, check whether the current tariff matches actual consumption and whether a different contract would be more suitable. Any potential savings should be assessed against contract terms, fees and conditions.
Workers can review whether their salary adjustments reflect changes in living costs, taking account of their employment contract and applicable collective agreements. Pensioners and eligible households may also wish to check official information about benefit uprating and available assistance.
A national inflation rate alone does not determine an individual’s entitlement to support. Eligibility depends on the rules of each programme, including income, household circumstances and other applicable requirements.
An emergency fund can reduce the need to borrow when unexpected bills arise. However, maintaining access to cash remains important, especially when essential expenses are rising.
For money that will not be needed immediately, comparing deposit rates, fees, withdrawal conditions and the protection available for deposits can help savers make informed decisions. Higher potential returns generally involve different conditions or risks, so there is no single option suitable for everyone.
Inflation can create pressure to borrow to cover ordinary expenses. Before taking on new debt, consider the total repayment cost, interest rate, fees and the effect on the monthly budget.
Be wary of financial products advertised as guaranteed ways to beat inflation. No investment offering market exposure is free from risk simply because prices are rising.
The European Central Bank (ECB) is responsible for monetary policy in the euro area. Its medium-term inflation target is 2%, measured using the Harmonised Index of Consumer Prices (HICP).
The objective is to maintain price stability rather than to prevent every individual price increase. The ECB uses policy interest rates and other monetary policy instruments to influence financing conditions and economic activity.
When inflation is persistently above target, tighter monetary policy can help reduce demand and ease price pressures over time. However, higher interest rates can also make borrowing more expensive for households and businesses.
Monetary policy does not work immediately. Its effects depend on economic conditions, lending decisions, consumer behaviour and developments such as energy prices or supply disruptions.
Governments have different tools. Depending on the measures adopted, fiscal policy can provide targeted support to vulnerable households, influence disposable income or address particular cost pressures. Such interventions need to be evaluated against their costs, distributional effects and potential impact on demand.
The ECB’s 2% target is a medium-term objective, not a promise that prices will remain unchanged or that the cost of living will return to its previous level.
Inflation is often discussed as a single percentage, but its consequences depend on household income, essential expenses and the pace at which prices change.
A decline in the inflation rate would mean prices are rising more slowly. It would not, by itself, reverse the increases that have already occurred. For households, meaningful relief depends on whether wages, pensions and other income can cover the new cost of everyday life.
In our assessment, economic policy should combine credible price stability with attention to households that have limited room to adjust their spending. Targeted assistance can help those facing the greatest pressure, while measures that improve productivity, competition and the supply of essential goods and services can support more sustainable outcomes.
Households, meanwhile, benefit most from clear information rather than promises of quick solutions. Tracking expenses, comparing prices and reviewing financial commitments can help, but individual budgeting cannot compensate fully for inadequate income or persistent increases in essential costs.
The central issue is the relationship between income and prices. Restoring purchasing power means ensuring that people can afford the goods and services they need, not merely reporting a lower inflation rate.
No. Lower inflation usually means prices are increasing more slowly. Prices generally fall only when there is deflation or when specific goods and services become cheaper.
Purchasing power reflects the quantity of goods and services that income can buy. To estimate changes in real income, compare the percentage change in income with the percentage change in consumer prices.
Official inflation is an average based on a representative basket of goods and services. Your personal spending pattern may differ, particularly if you spend a larger share of your income on housing, food, energy or transport.
Only if it keeps pace with the prices relevant to your spending. If income rises by less than inflation, purchasing power generally declines, all else being equal.
The ECB aims for 2% inflation over the medium term across the euro area, measured by the Harmonised Index of Consumer Prices. This is a monetary policy objective, not a guarantee that every household will experience the same rate of inflation.
1. National Statistics Institute (INE) — Flash estimate of the Consumer Price Index (CPI), September 2026 — https://www.ine.es/dyngs/Prensa/en/adIPC0926.html
2. Eurostat — Euro area annual inflation up to 3.8% — Flash estimate, September 2026 — https://ec.europa.eu/eurostat/en/web/products-euro-indicators/w/2-02102026-ap
3. European Central Bank (ECB) — Two per cent inflation target — https://www.ecb.europa.eu/mopo/strategy/pricestab/html/index.es.html
Contact : info@francealyom.com